
Blogs
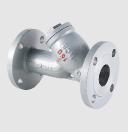
Pipeline systems require effective protection methods to maintain continuous fluid transportation and equipment stability. An ANSI Y Type Strainer offers a practical approach for filtering solid particles before they reach sensitive components. Its specially designed structure makes it suitable for applications where space efficiency and reliable filtration are important considerations.
The body shape of an ANSI Y Type Strainer resembles the letter “Y,” which creates a direct flow path while providing a separate chamber for collecting impurities. Inside the chamber, the filter element captures unwanted materials from liquids or gases. This design helps reduce the risk of blockage and supports consistent pipeline performance.
One important feature of this strainer is its simple maintenance process. During operation, particles gradually accumulate inside the screen area. Regular inspection and cleaning allow the equipment to maintain proper flow conditions. The removable screen design makes maintenance work more convenient for industrial teams.
ANSI Y Type Strainer products are widely applied in systems involving water circulation, cooling equipment, compressed air networks, and process pipelines. They are often installed before pumps, control devices, and measurement instruments to provide additional protection. By reducing contamination risks, these strainers help improve the stability of connected equipment.
When choosing an ANSI Y Type Strainer, engineers usually consider several technical factors. These include pipeline diameter, working pressure, fluid properties, temperature requirements, and filtration level. Selecting a suitable configuration ensures compatibility with the entire system and supports efficient operation.
Manufacturing quality is also an important factor for industrial applications. A well-produced strainer requires accurate dimensions, reliable sealing performance, and proper inspection procedures. These elements influence the durability and operational reliability of the product in demanding environments.
The development of industrial automation and advanced production systems has increased the demand for dependable pipeline accessories. Filtration components such as the ANSI Y Type Strainer continue to provide valuable support by helping maintain clean fluid pathways and protecting important machinery.
With its practical structure, flexible installation options, and reusable filtering element, the ANSI Y Type Strainer remains a useful choice for many industrial pipeline projects. It combines functional design with maintenance convenience, making it suitable for a wide range of fluid control applications.
Architectural Tempered Glass for Window, Balcony & Partition Applications Weifang Star Glass
By worldsou, 2026-07-31
Tempered glass is a special kind of glass that is made to be very strong and safe. It's used in many places, like windows, balconies, and partitions in buildings. At Star Glass, we make high-quality architectural tempered glass that meets the needs of our customers. Our glass is designed to be both beautiful and safe, making it a popular choice for homes and businesses. Whether you're looking to add a stylish touch to your balcony or need a sturdy partition for your office, Star Glass has the perfect solution for you.
Where to Find High-Quality Architectural Tempered Glass for Wholesale Purchases
If you're looking to buy architectural tempered glass, Star Glass is the place to go. We offer a wide range of options for wholesale purchases, making it easy for businesses and contractors to get what they need. You can visit our website or contact our sales team to learn more about our products and pricing. We pride ourselves on providing excellent service to our customers. When you buy from us, you can be sure that you are getting top-notch glass that has been made with care. Our glass is not only strong, but it also looks great. We have different sizes and styles available, so you can find the right fit for any project. Plus, our team can help you choose the best options for your needs. Whether you are working on a new building or a renovation, we can assist you in finding the right tempered glass . Ordering is simple, and we work hard to deliver your products on time. Star Glass is here to support you every step of the way, ensuring that your project is a success.

How Architectural Tempered Glass Enhances Safety and Aesthetic Appeal
Using architectural tempered glass in buildings adds a lot of value. First, it is much safer than regular glass. If it breaks, it shatters into tiny, blunt pieces instead of sharp shards. This feature makes it a great choice for places where safety is important, like schools or homes with children. Imagine a beautiful balcony made of tempered glass. Not only does it look nice, but it also keeps everyone safe. The clear glass allows light to come in, creating a bright and welcoming space. In addition to safety, the aesthetic appeal of tempered glass is remarkable. It gives a modern and sleek look that can elevate any space. For example, using tempered glass partitions in an office can create a stylish separation between work areas without making the space feel closed off. It can make the area look bigger and more open. Star Glass offers various designs and finishes, so you can pick what matches your style best. From clear glass to frosted options, there’s something for everyone. You can also use colored glass for a unique touch. Many people choose tempered glass sheet for their homes because it adds elegance. Whether it's for a stunning window view or a chic balcony, glass from Star Glass enhances the beauty of any space while keeping safety in mind.
Where to Source Affordable Yet Premium Architectural Tempered Glass Products
If you are looking for high-quality tempered glass for windows, balconies, or partitions, it is important to know where to find it. One great place to start is by visiting local glass suppliers or manufacturers. Companies like Star Glass offer a variety of architectural tempered glass products that are both affordable and premium. When you visit these suppliers, ask about the different types of tempered glass they have. You want to find glass that is strong, durable, and safe. You should also consider buying directly from manufacturers. Sometimes, they offer lower prices because you are buying straight from the source. This means you may be able to get premium products at a better price. Additionally, when you buy from a manufacturer, you can often get special deals or bulk discounts if you need a lot of glass. Lastly, don’t forget to ask about delivery options. Some companies, like Star Glass, provide delivery services, which can save you time and effort. By exploring different sources and comparing prices, you can find high-quality tempered glass that fits your budget. Remember, it is essential to choose a reliable supplier to ensure you get the best glass for your project.
Common Usage Issues with Architectural Tempered Glass and How to Avoid Them
While architectural tempered glass is strong and safe, there are some common problems that people face when using it. One issue is improper installation. If the glass is not installed correctly, it can break or crack easily. To avoid this, always hire experienced professionals to install your tempered glass. They know how to handle the glass safely and will ensure it is installed properly. People also sometimes forget to clean tempered glass properly. Using harsh chemicals or rough materials can scratch the surface and damage the glass. To keep your glass looking great, use a soft cloth and mild soap. This will help maintain its clarity and strength. Finally, temperature changes can cause issues if glass is not designed to handle them. For example, if it's very hot outside, the glass can expand. If it is too cold, it can contract. This can lead to cracks. To avoid this, make sure you choose full tempered glass that is suitable for your climate. Star Glass offers a range of products that are designed to withstand different weather conditions. By being careful with installation and maintenance, you can enjoy the beauty and safety of tempered glass without facing common problems.
How to Ensure Compliance with Building Codes When Using Tempered Glass
When you use architectural tempered glass in your home or building, it is very important to follow local building codes. These codes are rules that make sure buildings are safe and up to standard. If you do not follow these codes, you could face serious problems later on. One of the best ways to ensure compliance is to research the specific building codes in your area. Every city or county may have different rules, so it is essential to know what applies to your project. Next, work with trusted suppliers like Star Glass. They are knowledgeable about building codes and can help you choose the right type of tempered glass that meets the requirements. They can provide you with documents and specifications that show the glass meets safety standards. Finally, always keep records of your purchases and installation. This can help show that you followed all the necessary steps to comply with building codes. By following these guidelines and working with experienced professionals, you can ensure that your use of tempered glass is safe and legal.
Coffee culture has become part of many people’s daily routines, and having an organized preparation area can improve convenience. Coffee Pod Drawers provide a dedicated storage method for coffee capsules, helping users maintain a clean and functional beverage station at home or in professional environments.
A common challenge for coffee lovers is managing different capsule types in a limited space. Without proper storage, coffee pods may be placed randomly on shelves, counters, or containers. Coffee Pod Drawers solve this issue by creating a specific location where capsules can be stored neatly and accessed easily.
The compact structure of these drawers makes them suitable for various settings. They can be placed beneath coffee machines, inside cabinets, or on countertops depending on the layout of the space. This flexibility makes them suitable for kitchens, meeting rooms, reception areas, and hospitality environments.
A practical coffee pod drawer often includes a smooth sliding system and a stable base structure. These features allow users to open the drawer comfortably while keeping the capsules protected. The internal arrangement can support organized placement, which helps users quickly find the coffee they want.
For businesses, maintaining a clean coffee area can influence the overall atmosphere of a workplace or customer space. Organized storage accessories reduce visual clutter and make beverage preparation more efficient. Employees and visitors can enjoy a simple process when preparing coffee drinks.
Home users can also benefit from better capsule management. Families with different coffee preferences can separate capsules according to taste, caffeine level, or daily usage habits. This organization makes it easier to maintain inventory and notice when supplies need to be replaced.
As kitchen accessories continue to develop, storage products are becoming more focused on combining practical functions with modern appearance. Coffee Pod Drawers provide a balance between convenience and design, allowing users to create a pleasant coffee corner without requiring complicated changes.
With their useful structure and flexible application, Coffee Pod Drawers offer an effective way to organize coffee capsules. They support a cleaner space, easier access, and a more enjoyable coffee preparation process for different users.
Veteran R&D Specialists Develop Stable Long-Lasting Gel Nail Polish Formulas Yiwu Manfi
By worldsou, 2026-07-31
MANNFI is a company that creates gel nail polish, and they are really good at it. Their team is made up of veteran specialists who have spent years learning how to make nail polish that lasts a long time and doesn’t chip easily. This is important for people who want their nails to look nice for a long time. MANNFI’s products are known for their quality and stability. A lot of customers trust MANNFI because they know they will get great gel nail polish that they can count on.
Veteran R&D Specialists Craft Premium Gel Nail Polish Formulas for Bulk Buyers
MANNFI has a team of experienced researchers and developers who know everything about making gel nail polish. These experts have worked in the beauty industry for many years. They understand what customers want and need. When they create new professional gel nail polish formulas, they think about things like color, shine, and how long the polish lasts. They also pay attention to how easy it is to apply the polish. This is really important for salons and businesses that buy nail polish in bulk. They want something that looks good and will not let their customers down. MANNFI's team works hard to test their products. They make sure that every batch of gel polish is perfect before it goes out to customers. They are always looking for ways to improve their formulas. For example, they might experiment with different ingredients that make the polish last longer or look shinier. This constant work means that MANNFI can offer the best products on the market. Bulk buyers can feel confident choosing MANNFI because they know they are getting top-quality polish that their customers will love.

Common Issues with Gel Nail Polish and How MANNFI Solves Them
Many people love gel nail polish, but there are some common problems. One big issue is that some gel polishes can chip or peel off too easily. This is frustrating because no one wants to spend time doing their nails just to have them look bad a few days later. Another problem is that some gels don’t cure properly under UV light, which can make the polish look dull or uneven. MANNFI understands these issues and has worked hard to solve them. They carefully choose their ingredients to ensure that their gel polish is strong and durable. They also test their formulas with different types of UV lights to make sure they cure perfectly every time. This means no more dull or uneven nails! MANNFI also focuses on creating colors that stay vibrant and true, even after weeks of wear. Customers love that their nails look fresh for a long time. MANNFI’s gel nail polish is made with long-lasting formulas, and this makes them a favorite among both nail technicians and everyday users. With MANNFI, people don’t have to worry about their nail polish chipping or fading quickly. It’s all about making sure customers have a great experience with their nails, and that’s what MANNFI is all about.
What Are the Benefits of Using Professional Gel Nail Polish in Your Business?
Using professional gel nail polish can be a great choice for any business that offers nail services. One of the biggest benefits is that gel nail polish lasts much longer than regular nail polish. While regular polish might chip or fade after a few days, gel polish can stay looking good for two to three weeks or even longer. This means that your clients will be happier because they won't have to come in for touch-ups as often. Happy clients are likely to return and recommend your services to their friends, which can help your business grow. Another benefit of using professional hard gel nail polish is that it dries quickly under a special light called a UV or LED lamp. This means that your clients can leave the salon without worrying about smudging their nails. They can go about their day right after their appointment! Plus, gel nail polish comes in many beautiful colors and finishes, including shiny, matte, and glittery options. This variety allows you to offer unique looks that can attract more customers to your business.
Where to Buy High-Quality Gel Nail Polish at Competitive Prices
Finding high-quality gel nail polish at a good price is important for any business. You want to give your clients the best without breaking the bank. One great place to shop for gel nail polish is online. Many websites offer a wide range of products, including MANNFI gel nail polish, at competitive prices. Online shopping allows you to compare different brands and prices quickly. You can also read reviews from other salon owners to see which products work best. It's also a good idea to look for special promotions or bundles. Many brands, including MANNFI, offer deals where you can buy multiple colors for a lower price. This way, you can stock up your salon with different shades without spending too much. Joining a professional beauty group or forum online can also help you discover where other professionals buy their supplies. Sharing tips and tricks with fellow salon owners can lead to finding the best places to purchase gel nail polish at great prices.
How Veteran R&D Insights Improve Gel Nail Polish Stability and Performance
Veteran research and development (R&D) specialists play a vital role in creating the best gel nail polish products. They have years of experience and knowledge about what makes a nail polish last longer and look better. One of the main focuses of R&D is to improve the stability of gel nail polish. Stability means that the polish won’t separate or change over time. This is important because it helps maintain the quality of the product from the moment it’s made until it’s used by a customer. In addition to stability, R&D specialists also focus on making glitter gel nail polish safe for users. They test for any harmful chemicals and work to create formulas that are gentle on the nails and skin. This is important for salons because clients want to know that the products being used are safe for them. By using insights from veteran R&D specialists, MANNFI ensures that its gel nail polish not only looks great but is also safe and reliable. This commitment to quality can help your business stand out and keep clients coming back for more beautiful nails.
The paper industry relies on a variety of functional materials to achieve specific surface characteristics, and Carboxylated Butadiene-Styrene Latex is among the materials frequently used in coating formulations. Its ability to function as a binder while supporting coating stability makes it suitable for many paper grades used in printing and packaging applications.
Carboxylated Butadiene-Styrene Latex is typically incorporated into coating mixtures containing pigments such as clay and calcium carbonate. The latex helps bind these particles together and anchor them to the paper surface. This interaction contributes to a more uniform coating layer and supports consistent product quality throughout production.
One advantage associated with Carboxylated Butadiene-Styrene Latex is its compatibility with high-speed paper manufacturing processes. The material can be formulated to maintain stable rheological properties, allowing coating operations to proceed efficiently. Consistent coating performance can contribute to smoother production workflows and reduced process variation.
Printability is another important consideration in paper manufacturing. Coated paper often requires a surface capable of receiving inks evenly while maintaining image clarity. Carboxylated Butadiene-Styrene Latex contributes to coating structures that help create smooth and controlled surfaces suitable for various printing methods.
Packaging materials also benefit from the use of Carboxylated Butadiene-Styrene Latex. Packaging papers and paperboards may require surface strength, coating integrity, and resistance to handling during transportation. The binder properties of the latex help support these requirements while maintaining production flexibility.
In specialty paper applications, manufacturers may adjust latex characteristics to achieve specific performance targets. Particle size distribution, carboxyl content, and formulation design can influence coating behavior. Through careful selection and testing, paper producers can develop products tailored to customer requirements.
Sustainability considerations are becoming increasingly important throughout the paper sector. Water-based coating systems containing Carboxylated Butadiene-Styrene Latex can be integrated into production processes designed to reduce solvent usage. This approach supports environmental objectives while maintaining functional performance.
As paper products continue to serve communication, packaging, and industrial markets, Carboxylated Butadiene-Styrene Latex remains an important component in coating technology. Its ability to support coating quality, process stability, and application versatility contributes to its continued use across a wide range of paper manufacturing operations.
Artificial Intelligence is reshaping industries across the United States, from healthcare and finance to retail, manufacturing, and logistics. Businesses are investing heavily in AI-powered solutions to automate workflows, improve customer experiences, and gain a competitive advantage. However, the success of every AI model depends on one crucial factor: high-quality data.
Many organizations focus on selecting the right AI framework or machine learning algorithm while overlooking the foundation of every successful AI initiative—data collection. This is where an AI Data Collection company becomes an invaluable partner. By delivering accurate, diverse, and ethically sourced datasets, these companies help organizations build AI systems that are reliable, scalable, and unbiased.
In this article, we'll explore why partnering with an AI Data Collection company is essential for every AI project and how it accelerates the journey from concept to production.
What Is an AI Data Collection Company?
An AI Data Collection company specializes in gathering, organizing, and preparing high-quality datasets used to train, validate, and test artificial intelligence and machine learning models. These companies collect data from multiple sources while ensuring accuracy, diversity, compliance, and proper labeling.
Depending on the AI application, data collection services may include:
- Image and video collection
- Audio and speech data collection
- Text and document datasets
- Sensor and IoT data
- Healthcare and medical data
- Retail and eCommerce datasets
- Autonomous vehicle data
- Human activity recognition datasets
Professional data collection companies also ensure that data is collected ethically and complies with privacy regulations such as GDPR, CCPA, and other industry-specific standards.
Why High-Quality Data Is the Foundation of AI Success
AI Models Learn Only from the Data They Receive
Artificial intelligence doesn't think like humans—it learns patterns from historical data. If the training data is inaccurate, incomplete, or biased, the AI model will produce unreliable predictions.
For example:
- A healthcare AI trained on incomplete patient records may provide incorrect diagnoses.
- A customer support chatbot trained with outdated information may generate inaccurate responses.
- A computer vision model trained with poor-quality images will struggle to recognize objects correctly.
An experienced AI Data Collection company ensures that datasets are accurate, balanced, and representative of real-world scenarios.
Better Data Improves Model Accuracy
Even the most advanced machine learning algorithms cannot compensate for poor-quality data.
Benefits of high-quality datasets include:
- Higher prediction accuracy
- Faster model training
- Reduced bias
- Better real-world performance
- Improved customer satisfaction
- Lower retraining costs
Simply put, better data leads to better AI.
Challenges of Collecting AI Training Data In-House
Many organizations initially attempt to collect training data internally. However, they often encounter several obstacles.
Limited Data Sources
Internal teams usually have access to only a limited amount of data, making it difficult to create diverse training datasets.
Time-Consuming Process
Data collection involves sourcing, cleaning, validating, organizing, annotating, and maintaining datasets. This process can consume months of engineering time.
Compliance Risks
Handling sensitive information requires compliance with privacy regulations and ethical standards. Failure to comply can result in legal and financial consequences.
Scalability Issues
As AI projects grow, organizations need millions of labeled data samples. Scaling in-house operations quickly becomes expensive and resource-intensive.
An AI Data Collection company eliminates these challenges by providing scalable, high-quality datasets tailored to specific AI use cases.
Key Benefits of Partnering with an AI Data Collection Company
Access to Diverse and High-Quality Data
AI performs better when trained on diverse datasets representing different demographics, environments, languages, and scenarios.
Professional data collection companies gather information from multiple trusted sources to improve model robustness.
Faster AI Development
Collecting data from scratch delays product launches.
A specialized AI Data Collection company accelerates development by providing ready-to-use datasets or managing end-to-end data collection workflows, allowing AI engineers to focus on model development instead of data sourcing.
Accurate Data Annotation
Data collection is only one part of the process.
Images, videos, text, and audio must be properly labeled before AI models can learn from them.
Professional annotation services ensure consistent labeling, improving training efficiency and model performance.
Reduced Bias
Bias in AI can lead to unfair decisions and inaccurate predictions.
Experienced data collection companies actively minimize bias by collecting balanced datasets across various demographics, geographic locations, and user behaviors.
Regulatory Compliance
Organizations operating in healthcare, finance, insurance, and other regulated industries must comply with strict privacy laws.
A trusted AI Data Collection company follows secure data handling practices while maintaining compliance with applicable regulations.
Industries That Benefit from AI Data Collection Services
Almost every industry building AI-powered solutions depends on reliable datasets.
Healthcare
Medical imaging, disease detection, patient monitoring, and clinical research all require accurately collected and annotated healthcare data.
Retail and eCommerce
Retail businesses use AI for personalized recommendations, inventory management, demand forecasting, and customer behavior analysis.
Financial Services
Banks and fintech companies rely on quality datasets for fraud detection, credit risk analysis, and regulatory compliance.
Automotive
Self-driving vehicles require millions of labeled images, videos, and sensor data samples to safely navigate real-world environments.
Manufacturing
Manufacturers leverage AI for predictive maintenance, quality inspection, robotics, and process optimization.
How to Choose the Right AI Data Collection Company
Not every provider offers the same level of expertise.
When selecting an AI Data Collection company, consider the following factors:
Industry Experience
Look for companies with proven expertise in your business domain.
Data Quality Standards
Ask about their validation process, annotation accuracy, and quality assurance methods.
Scalability
Choose a partner capable of handling both small pilot projects and enterprise-scale AI initiatives.
Security and Compliance
Verify that the company follows industry-standard security practices and complies with relevant privacy regulations.
End-to-End Services
The best providers offer comprehensive solutions, including data collection, cleaning, annotation, validation, and dataset management.
Why Businesses Choose OneTechSolutions.ai
At OneTechSolutions.ai, we understand that successful AI starts with exceptional data.
Our team provides customized AI data collection services designed to support businesses across industries with scalable, accurate, and ethically sourced datasets. From image and video collection to text, speech, and industry-specific data, we help organizations build AI models that perform with confidence.
By combining domain expertise, rigorous quality assurance, and scalable data operations, we empower businesses to accelerate AI innovation while reducing development risks.
Conclusion
Artificial intelligence is only as intelligent as the data used to train it. Investing in quality data collection is not an optional step—it is the foundation of every successful AI initiative.
Partnering with a trusted AI Data Collection company enables organizations to access reliable, diverse, and compliant datasets that improve model accuracy, reduce bias, accelerate development, and maximize long-term ROI.
Whether you're developing predictive analytics, computer vision systems, conversational AI, or autonomous technologies, choosing the right data collection partner can make the difference between an average AI solution and an exceptional one.
If your organization is ready to build AI with confidence, OneTechSolutions.ai is here to provide the high-quality data your next AI project deserves.
PW Consulting: Thickener Market to reach USD 14,283M by 2032 at 5.8% CAGR
By pmarketresearch, 2026-07-30

Thickener Market — 2026 Strategic Briefing
As PW Consulting’s senior industry analyst, I present a concise, strategy-focused introduction to our comprehensive Thickener Market study (base year 2025). This briefing is designed to orient C-suite and commercial leaders facing critical 2026 choices — capital allocation, portfolio reshaping, sourcing strategy, and M&A prioritisation. We deliberately present high-level, data-driven insight here to demonstrate the analytical rigor behind the full study while omitting the proprietary segment-level tables and granular regional/application splits that are available only in the full report.
Thickener Market
Macro snapshot you can act on
- Market trajectory: The global thickener market expanded steadily through 2020–2025, reaching an estimated USD 9.65 billion in 2025. Our forecast model projects continued expansion through 2032, driven by both food & beverage and industrial end‑markets, resulting in a market size of roughly USD 14.28 billion by 2032 under a central scenario.
- Growth rate: The forecast period (2026–2032) assumes a compound annual growth rate (CAGR) of approximately 5.8%, reflecting the combined effect of product innovation, sustainability-driven reformulation, and selective industrial demand resurgence.
- Market structure: The sector is moderately concentrated: the three-largest firms control the majority of organised volume and value-added solutions, and the top five together exert significant pricing and distribution influence. This concentration underpins both competitive defensive moves and attractive bolt-on M&A opportunities for mid-sized players.
What’s moving the market in 2026 — dynamics and headwinds
- Regulatory and sustainability pivot: Policymaker momentum is accelerating substitution away from certain synthetic polymers toward biodegradable and bio‑based thickeners. European regulatory shifts and procurement standards are increasing adoption rates of bio-based solutions — a trend that now shapes R&D priorities and product roadmaps.
- Raw material volatility: Cost pressure in key natural hydrocolloid feedstocks has intensified. For example, xanthan feeders experienced a meaningful Q1 2026 uplift in FOB pricing in major supply hubs, compressing formulators’ margins and raising urgency for procurement hedges, alternative sourcing strategies, and formulation optimisation.
- Industrial and water-management innovation: Equipment suppliers and miners continue to invest in throughput and efficiency upgrades for thickening processes. Recent capital projects and new product introductions are shortening deployment cycles for select industrial thickening applications.
- Operational compliance risks: Several emerging markets have reported rising effluent and wastewater treatment loads related to chemical processing, increasing compliance costs and creating local operating constraints for some manufacturers.
Competitive landscape — positioning and strategic posture
The market is served by a mix of global agribusiness ingredient players, speciality hydrocolloid firms, and chemical giants. Each plays a distinct role along the value chain and pursues specific go-to-market strategies:
Thickener Market
- Cargill — Global agrifood integrator with extensive hydrocolloid and starch-based offerings, increasingly positioning around clean-label and plant-based claims to capture food & beverage reformulation opportunities.
- Ingredion — Specialist in starch and fermentation-derived thickeners with broad application expertise in food, beverage and personal care, leveraging application labs to drive specification wins.
- Archer Daniels Midland (ADM) — Large-scale starch and corn-derived supplier focused on industrial scale and vertical raw-material integration, enabling competitive cost structures for commodity-thickener supply.
- Kerry Group & Tate & Lyle — Mid-to-large speciality ingredient firms combining hydrocolloids, pectins and application know-how to service premium food and beverage customers seeking clean-label replacements.
- CP Kelco — A category specialist in xanthan, gellan and carrageenan, increasingly emphasising sustainability upgrades and decarbonisation in its plant investments.
- BASF, Dow, DuPont, Ashland, AkzoNobel, Elementis — Chemical and speciality chemical players focused on synthetic, acrylic and cellulose ether thickeners for paints, coatings, construction, personal care and industrial applications. Their advantage lies in polymer technology, formulation performance and global coatings distribution channels.
Recent public developments illustrate these dynamics: facility decarbonisation projects, small-scale packaged thickening equipment launches for decentralised wastewater treatment, and commissioning of plant-level throughput upgrades in mining — all reinforcing a differentiated set of threats and opportunities across segments.
Thickener Market
What the PW Consulting report delivers (actionable, practitioner-focused)
- Proprietary market-sizing model: historical (2020–2025) reconciliation and a configurable forecast engine (2026–2032) that lets users run custom scenarios for price, raw material shock, and regulatory adoption paths.
- Segment and application architecture: a structured taxonomy linking type, formulation, and end-use (note: the public brief omits granular split tables — those are provided in the full report to paid subscribers).
- Pricing and margin analytics: pass-through sensitivity models that quantify margin impact from feedstock moves and differential adoption of bio‑based alternatives.
- Supply-chain mapping: supplier concentration matrices, critical-node risk heatmaps, and sourcing optimisation playbooks for both commodity and speciality feedstocks.
- Regulatory & sustainability impact assessment: scenario simulations on policy adoption (EU, US, India) and their impact on product portfolios and compliance costs.
- Competitive benchmarking: capability heatmaps across production footprint, innovation intensity, go-to-market coverage, and sustainability credentials, including M&A screening criteria for strategic acquirers.
- Practical go-to-market tools: commercial pricing playbooks, sample RFP language for procurement, and an 18-month action plan template for product relaunches centered on clean-label claims.
- Primary research: synthesis of over 50 stakeholder interviews (manufacturers, formulators, major end users, and regulators), corroborating quantitative findings with real-world commercial intelligence.
Strategic implications — recommended actions for 2026 decision cycles
- Prioritise bio-based and clean-label NPD: Fast-track reformulations where regulatory risk is highest and where premiumisation supports sustainable margin capture. Pilot launches should be paired with claims substantiation and customer co‑development agreements.
- Hedge raw-material exposure: Implement a layered procurement strategy combining long-term contracts, regional multi-sourcing, and limited vertical integration where economics justify. Pay special attention to high-volatility hydrocolloids.
- Segment-driven capacity strategy: Delay broad-spectrum greenfield investment; instead, pursue modular capacity that can be repurposed across types as demand shifts — particularly relevant for players exposed to both food and industrial applications.
- Targeted M&A and partnerships: For mid-sized players, focus on bolt-on acquisitions that add unique hydrocolloid chemistries or regional market access. For large firms, aim to secure specialty portfolios that accelerate clean-label leadership.
- Operational sustainability as differentiation: Invest selectively in decarbonisation and effluent management projects that reduce regulatory risk and shorten customer approval cycles in sustainability-focused procurement processes.
- Customer-centric commercial models: Introduce value-based pricing and technical support bundles for formulators to justify premium for higher-specification, sustainable thickeners.
- Digital enablement: Adopt advanced demand-forecasting and RI/OT tracking to reduce batch variability and improve raw-material yield — quick wins that protect margins under price volatility.
How to apply these insights — by archetype
- Ingredient manufacturers: Use the report’s supplier risk and pricing modules to set a 12–24 month procurement and CapEx plan; prioritise specialty lines with higher margin resilience to feedstock shocks.
- Formulators and brands: Leverage the end‑use performance matrix to identify candidate thickening systems that meet both sensory and sustainability thresholds; deploy co-funded pilot programmes with suppliers to accelerate time-to-market.
- Industrial end users (mining, wastewater, coatings): Adopt the equipment and throughput case studies to benchmark retrofit vs. replacement investments and quantify the total cost of ownership for thickening solutions.
In short, the thickener market in 2026 presents a mix of rising demand and increasing technical/regulatory complexity. The growth runway is clear at a macro level; the near-term competitive prize belongs to organisations that can combine formulation agility with disciplined procurement and credible sustainability narratives.
Next steps — where to find the full intelligence
This briefing intentionally omits the granular region-by-region and application-by-type splits and some proprietary pricing matrices to preserve the commercial value of the full study. PW Consulting’s complete Thickener Market report contains those detailed tables, the interactive forecast workbook, competitor scorecards, and a bespoke scenario workshop kit to support your 2026 planning cycle. Contact PW Consulting or visit the report landing page to access the full dataset and schedule a strategy workshop to translate the analysis into a concrete 18-month action plan.
For detailed analysis of this topic, please visit the official page: Thickener Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Triacetin Market Eyes USD 408.1M by 2032 with 5.12% CAGR — PW Consulting
By pmarketresearch, 2026-07-30

Triacetin Market 2026 Strategic Outlook — A PW Consulting Briefing
As PW Consulting’s lead industry analyst, I present a concise, decision-focused introduction to our full Triacetin Market study. This briefing surfaces the strategic implications that will matter most to commercial and corporate leaders in 2026 — highlighting where value is created, which risks require mitigation, and what to prioritize in capital and commercial plans. It intentionally demonstrates analytical depth while preserving the granular segmentation and proprietary tables for readers who access the full report.
Triacetin Market
Why Triacetin Deserves Boardroom Attention in 2026
- Triacetin is no longer a niche intermediate. Its multi-sector role — as a plasticizer/solvent/humectant and as an excipient in food, tobacco, pharmaceutical, and personal-care formulations — gives it strategic relevance for companies spanning chemicals, packaging, consumer goods, and regulated health markets.
- Market momentum is clear: after steady growth through the first half of the decade, the triacetin market reached an elevated base by 2025 and is projected to grow at a mid-single-digit compound annual growth rate (CAGR) of 5.12% over our 2026–2032 forecast window. By the end of that horizon the market is forecast to be materially larger than it was in 2025, reflecting both demand expansion and quality-driven premiumization.
- These dynamics create a strategic inflection point. Companies that move early to secure compliant, high-purity supply chains and to re-price value-added grades will capture disproportionate margin and commercial advantage.
What the Full Report Delivers — Practical, Executable Outputs
Our full study is constructed to support immediate decision-making. It contains:
Triacetin Market
- Market sizing and trend narratives covering the historical period through 2025 and a detailed forecast to 2032, with stress-tested scenarios tied to regulatory and feedstock shifts.
- Segment-by-grade and end‑use analyses (product, grade, and sector dynamics), with actionable implications for R&D, sales prioritization, and inventory strategy. (Note: granular segment tables are available in the premium download.)
- Supply-chain anatomy — feedstock cost curves, purification pathways for pharma and food grades, and a supplier risk heatmap.
- Regulatory matrix summarizing jurisdictional requirements and compliance timelines for food-contact, pharmaceutical excipient, and inhalation/consumer aerosol applications.
- Commercial playbooks: price-renegotiation templates, quality-differentiation strategies, go-to-market options by customer archetype, and a short-list of likely M&A targets and partnership types.
- Executive-ready dashboards: sensitivity models for raw-material shocks and regulatory tightening, plus supplier scorecards for rapid procurement decisions.
Key Dynamics Shaping Strategy in 2026
- Regulatory tightening. European authorities introduced stringent documentation and migration thresholds for food-contact plasticizers in 2025, imposing new analytical and traceability obligations. Concurrent regional amendments to legacy frameworks have effectively raised the bar for high‑purity claims. Separately, UK rules for e-liquids and aerosols now demand toxicological substantiation at typical formulation loadings. The net effect: suppliers face higher compliance costs and customers (especially in food and pharma) are increasingly risk-averse.
- Feedstock evolution. The supply base is evolving from an overwhelmingly synthetic‑glycerin orientation toward incremental sourcing of vegetable-origin glycerin and discounted crude glycerol from biodiesel side‑streams that can be upgraded for higher-value grades. These shifts create both margin opportunities for quality arbitrage and complexity for procurement that lacks feedstock flexibility.
- Commercial pressure and pricing behavior. Leading producers signaled commercial rebalancing in 2025 through staged price adjustments on technical grades. Those moves are an early indicator of how producers will attempt to recoup compliance and feedstock costs — while simultaneously protecting premium channels that demand certified purity.
- Consolidation and differentiated portfolios. The market is characterized by a limited number of global producers with established specialty portfolios — from technical resins to pharmacopeial excipients. This structure favors firms that can scale high‑purity production while maintaining a cost-competitive footprint for commodity grades.
Competitive Landscape — Strategic Profiles
Five legacy and specialty players anchor the triacetin value chain today. Each presents distinct implications for partners, buyers, and investors:
Triacetin Market
- Eastman Chemical Company — A global integrator with a technical-grade triacetin portfolio positioned for cellulosic resins, acetate filters, and industrial uses. Recent pricing actions in 2025 reflect active commercial management of supply and a willingness to monetize differentiated capacity.
- Daicel Corporation — Production-linked capabilities integrated with tri‑acetyl cellulose manufacturing provide downstream synergies for food, pharmaceutical, and technical customers. Plant-level integration is a strategic advantage where regulatory traceability and consistent quality are prioritized.
- LANXESS — Offers glycerol triacetate products targeted at polymer and PVC applications. Their focus on polymer performance aligns them with customers seeking formulation-level improvements rather than commodity substitution.
- Polynt S.p.A. — Specialty glycerol esters produced at targeted sites for food packaging, confectionery, and pharmaceutical segments. These specialty routes can command premium positioning when combined with validated migration and toxicology dossiers.
- BASF SE — Markets triacetin variants as excipients and solvents for pharmaceuticals and personal care. A strong global regulatory and product-dossier capability makes such firms attractive partners for customers facing tightened compliance regimes.
Collectively, these incumbents demonstrate two strategic archetypes: integrated producers who leverage downstream applications, and specialty manufacturers who monetize high-purity, regulatory-ready supply. The competitive balance favors those who can couple quality credentials with flexible feedstock sourcing.
Strategic Imperatives — What Leaders Should Do in 2026
- Invest in compliance-first quality systems. High-purity traceability (analytical documentation, migration testing, toxicology dossiers) is table stakes in food and pharma channels. Firms without documented supply chains risk losing shelf space to certified competitors.
- Build feedstock optionality. Dual-sourcing strategies that combine synthetic and renewable glycerol routes — plus partnerships with biodiesel processors for crude glycerol streams — reduce exposure to single-supplier shocks and enable margin capture through feedstock arbitrage.
- Differentiate with premium grades. Where regulation tightens, willingness-to-pay bifurcates. Companies should develop value-based pricing for certified grades and convert commoditized relationships into long-term supply agreements with escalation clauses tied to compliance costs.
- Re-evaluate commercial terms and inventory policy. Price uplift tendencies among leading producers in 2025 illustrate the need for agile contracting and inventory hedges for at-risk channels, particularly where product continuity is mission-critical.
- Pursue targeted M&A and capacity partnerships. Given the importance of validated documentation and production know-how, bolt-on acquisitions of specialty capacity or JV stakes in purification assets can accelerate market access and shorten time-to-compliance.
Where the Full Report Adds Value
This briefing highlights the high‑impact considerations for 2026, but the full PW Consulting report provides the operational detail required to act: granular supply-and-demand tables, grade‑level price sensitivities, regional regulatory comparators, supplier scorecards, and downloadable negotiation templates. Practitioners will find stepwise playbooks for procurement, R&D prioritization, and regulatory readiness — all built from primary interviews and validated datasets.
Next Steps — How PW Consulting Partners with You
Our advisory services translate this strategic insight into executable plans: supplier due diligence, commercial transformation roadmaps, regulated‑product launches, and M&A diligence. If your 2026 plan contemplates capacity expansion, higher‑purity product introductions, or reshaping procurement to capture feedstock arbitrage, PW Consulting can deliver tailored scenario analyses and a prioritized action agenda.
To access the proprietary segmentation tables, regulatory summaries, and supplier concentration metrics that underpin these recommendations, please visit the full report page. The downloadable study includes appendices with methodological transparency, primary sources, and the models you can export directly into your planning tools.
Triacetin’s near-term trajectory will be driven as much by regulatory and feedstock shifts as by pure demand growth. Companies that align quality, sourcing flexibility, and commercial pricing in 2026 will define who thrives in the expanding market to 2032.
For detailed analysis of this topic, please visit the official page: Triacetin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polyimide (Kapton) Tape Market to Reach USD 2,234M by 2032 at 9.2% CAGR
By pmarketresearch, 2026-07-30

Polyimide Tape (Kapton Tape) Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused preview of our full Polyimide Tape (Kapton Tape) Market study — designed to equip executive teams with the strategic vantage required for confident 2026 planning. This preview synthesizes market momentum, competitive moves, regulatory inflection points, and action-oriented frameworks from our full report. It intentionally highlights analytical depth while omitting the granular segment-level tables and privileged forecasts locked in the full study — a deliberate “trailer” meant to show capability and drive you to the complete dataset and playbooks.
Polyimide Tape (Kapton Tape) Market
Why this market matters to 2026 strategy teams
-
Market trajectory: The polyimide tape market is on a sustained growth path. Measured in USD Million, the market expanded from a multi-hundred million base in 2020 to an estimated USD 1,210.0 Million in 2025, and our modeling projects robust expansion through 2032, reaching over USD 2,200 Million in the baseline forecast horizon. This equates to a compound annual growth rate (CAGR) of approximately 9.2% across the forecast period.
Polyimide Tape (Kapton Tape) Market -
Why growth is durable: Demand drivers are both secular and cyclical — from the continued miniaturization and thermal management needs in semiconductors and advanced electronics, to scaling applications in EV power electronics, aerospace & defense heat shielding, and precision manufacturing processes that require high-temperature masking and electrical insulation.
Polyimide Tape (Kapton Tape) Market -
Decision relevance for 2026: With the market in an acceleration phase, 2026 is the pivotal year for capital allocation and supply-chain repositioning. Actions taken this year — capacity commitments, JV terms, sourcing contracts, or product-line pivots — will define market share trajectories through the late-2020s.
What our report delivers (practical, executable content)
-
Proven forecasting engine: A transparent, scenario-based model calibrated to historical performance (2020–2025) and forward-tested against alternative macro and industry-specific scenarios. The model is deliverable in an interactive workbook so planners can stress-test assumptions (e.g., capex delays, raw-material shocks, trade-control scenarios).
-
Supply-chain stress tests: Step-by-step simulations that quantify the operational and P&L impact of supply disruptions, including lead-time elongation, single-source dependencies, and raw-material price spikes. Each test links to mitigation playbooks (dual sourcing, hedging strategies, consignment agreements).
-
Commercial playbooks: Go-to-market modules covering B2B contracting (volume discounts, strategic alliances with OEMs), channel optimization, and pricing levers for different product variants. These playbooks are built for commerce teams ready to deploy within 90–180 days.
-
Regulatory risk matrix: A prioritized map of current and plausible export-control and materials regulations, with hedge strategies (compliance architectures, jurisdictional sourcing options, licensing roadmaps) for minimizing production and market access interruptions.
-
M&A and capex scoreboard: Rigorous target evaluation templates for acquisition or greenfield moves, including synergy calculators, integration scorecards, and break-even analyses tied to volume and price scenarios.
-
Supplier and technology scorecards: Comparative matrices that rate raw-material suppliers, tape producers, adhesive technology providers, and end-use integrators across metrics of capacity, geographic risk, technological fit, and ESG compliance.
Competitive landscape — what incumbents and new entrants are signaling
The market exhibits a moderate concentration profile: the top three providers account for a meaningful share of industry sales, and the top five further increase concentration — a dynamic that favors incumbents with scale, proprietary film formulations, and deep established relationships in semiconductor, aerospace, and industrial OEM channels. That concentration creates both barriers and opportunities: scale-sensitive players can exert pricing discipline and invest in capacity or specialty R&D, while nimble suppliers can carve higher-margin niches through customization and rapid-response service models.
-
DuPont — a strategic bellwether. With branded Kapton film and tape, DuPont has demonstrated a willingness to invest in capacity to secure long-term demand. A notable expansion completed in 2024 underscores how incumbent producers are pre-empting future shortages and locking in feedstock throughput.
-
3M Company — product-led differentiation. 3M’s ongoing product innovation for extreme-temperature masking in semiconductor fabrication illustrates how technology variants can open premium segments within existing markets.
-
Nitto Denko — regional capacity shifts. Recent expansions targeted at EV power electronics and EMI shielding signal demand-side shifts: producers are reorienting capacity to high-growth applications tied to electrification and miniaturized power systems.
-
Specialized and distributor players (e.g., Scapa Group, Saint-Gobain, Fralock, CS Hyde, KaptonTape.com, TapeCase) — collectively these players serve high-touch, application-specific needs — custom slitting, adhesive tuning, ESD-safe solutions, and small-batch specialty runs. These providers are attractive for OEMs needing rapid prototyping and specialized certifications.
Regulatory and raw-material dynamics that will shape 2026 choices
-
Raw-material cost structure: Production depends on aromatic polyimide monomers and specialty resins that are capital- and technology-intensive to produce. Elevated upstream costs meaningfully affect unit economics and industry margins, necessitating tighter procurement strategies and cost pass-through contract clauses for buyers and producers alike.
-
Export controls and trade policy: Multiple jurisdictions updated controls on advanced materials and processing technologies in 2024–2025, with additional measures impacting polyimide-related supply chains announced or enacted in 2025. These measures introduce new compliance obligations and potential sourcing constraints. Strategic responses include diversified sourcing footprints, licensing contingency plans, and proactive dialogues with trade authorities.
-
Geopolitical concentration risk: Manufacturer footprints and raw-material supply are geographically clustered in certain regions, creating systemic exposure. A pragmatic 2026 strategy must quantify that exposure and, where economically viable, implement hedges — whether via inventory buffers, local-sourcing agreements, or co-investments in regional production.
Strategic options for 2026 — prioritized and actionable
-
Option A — Secure supply, protect margins: For volume-dependent manufacturers, prioritize multi-year off-take contracts with staged price indexes tied to validated raw-material baskets. Combine contracts with rights of first refusal on capacity expansions to prevent spot-market squeezes.
-
Option B — Differentiate through specialization: Invest in adhesive chemistry and slitting capabilities that serve high-margin niches (extreme-temperature, EMI management, aerospace-grade certification). For many mid-sized players, this route yields higher returns than scale alone.
-
Option C — Strategic partnerships and co-investments: Where regulatory and capex constraints deter greenfield projects, consider joint ventures with incumbents or end-users. Co-location with semiconductor fabs or EV powertrain assembly lines shortens logistics and improves responsiveness.
-
Option D — M&A for capability and market access: Target tuck-ins that add adhesive technology, specialty slitting, or regional footholds. Use the M&A scoreboard in our full report to assess payback timing under differing market growth sensitivities.
How to use this preview in your 2026 planning
Leaders should treat this preview as a decision trigger. Use it to align stakeholders on three immediate steps for 2026:
-
Run a 90-day supply-chain diagnostic using scenario inputs (included in the full deliverable) to quantify single-source exposures and identify the top three suppliers where contract renegotiation or capacity options are urgent.
-
Commission a product-differentiation audit to evaluate whether premium adhesive formulations or specialized tape geometries could unlock new OEM contracts with better gross margins.
-
Engage in regulatory horizon scanning and secure legal counsel to model licensing or export permutations relevant to your sourcing jurisdictions and end-markets.
Conclusion — the strategic pay-off
The Polyimide Tape market is moving from steady growth to strategic inflection. With market size expanding from roughly USD 790 Million in 2020 to an estimated USD 1,210 Million in 2025 and a projected climb toward and beyond USD 2,200 Million by 2032 at a ~9.2% CAGR, the timing for decisive action is now. Whether your priority is supply security, margin expansion through technology, or acquisitive growth, 2026 decisions will disproportionately determine outcomes through the rest of the forecast decade.
PW Consulting’s full report provides the granular segmentation, supplier-level financials, and executable playbooks required to translate these strategic options into measurable results. For executives who must convert insight into strategic advantage this year, our complete study and the accompanying analytical toolkit are the next logical step.
For detailed analysis of this topic, please visit the official page: Polyimide Tape (Kapton Tape) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lithium‑Ion Electrolyte Market Set for 12.94% CAGR (2026–2032)
By pmarketresearch, 2026-07-30

Lithium‑Ion Battery Electrolyte Market — Strategic Imperatives for 2026
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused introduction to our latest market intelligence on the Lithium‑Ion Battery Electrolyte market. This briefing translates the report’s core strategic value into concrete decision levers for 2026 while preserving the gated, high‑value datasets that underpin our forecasts. The analysis is anchored to a 2025 base year and a 2026–2032 forecast window, with the market tracked from 2020 through 2025. Our bottom‑up projection shows the market growing at a compound annual growth rate (CAGR) of 12.94% across the forecast horizon — expanding from an estimated ~USD 7.8 billion in 2025 toward a multi‑billion dollar opportunity by 2032. This trajectory creates both structural winners and tactical risks for manufacturers, OEMs, raw‑material suppliers, investors, and policy stakeholders.
Lithium Ion Battery Electrolyte Market
Why this research matters for 2026 decisions
-
Timing of capital deployment: 2026 is a pivotal inflection point for many firms that committed to capacity expansions in the 2022–2025 cycle. Our analysis helps executives determine whether to accelerate, delay, or reconfigure capital allocation based on demand elasticity and supply‑side constraints.
Lithium Ion Battery Electrolyte Market -
Supply chain resilience and IRA‑era localization: Policy drivers and buyer commitments mean near‑term commercial qualification cycles and local content considerations have outsized value. The report maps where localized supply matters most to cell makers and battery integrators.
Lithium Ion Battery Electrolyte Market -
Raw‑material volatility and margin protection: Electrolyte makers face concentrated upstream supply risk (notably LiPF6) and episodic price spikes. We model price pass‑through, hedging approaches, and margin sensitivity under alternative commodity paths to inform procurement and contracting strategies.
-
M&A and partnership windows: Consolidation is emerging as a strategic route to secure capacity, access proprietary formulations, or accelerate geographic footprint. Our competitive triangulation identifies the classes of targets that will deliver the fastest strategic payback.
What the full report provides (operationally focused)
-
Market sizing and multi‑scenario forecasts (2026–2032) driven by cell chemistry adoption curves, EV and stationary storage demand scenarios, and OEM battery roadmaps.
-
Segment mapping (by region, electrolyte type, and end‑use application) with demand drivers and bottom‑up capacity reconciliation. Note: detailed segment tables and downloadable models are retained in the full report to preserve their commercial value.
-
Supply chain and cost‑curve analysis that connects raw‑material pricing, purification yields, and tolling economics to unit cost for electrolytes and salts.
-
Competitive benchmarking and capability matrices that score incumbent producers on purity technology, regulatory compliance, localized manufacturing, and customer port‑folios.
-
Regulatory, environmental, and safety risk assessments — including permitting timelines, hazardous‑materials handling constraints, and compliance pathways across major markets.
-
Go‑to‑market playbooks for producers: contract templates, qualification timelines for OEMs, customer segmentation, and premium formulation commercialization steps.
-
Investment decision tools: sensitivity analyses, NPV templates, and break‑even models for greenfield vs retrofit plants and for pursuing upstream integration into salts and additive supply.
-
Prioritized M&A target shortlists and diligence checklists for strategic buyers and private equity, based on technology, capacity, and route‑to‑market fit.
Methodology and confidence
-
Base: 2025 as the fiscal base year with historical trend analysis from 2020–2025.
-
Projections: Multi‑model forecasting that combines bottom‑up plant builds, OEM qualification lags, and demand curves for EV, consumer electronics, and energy storage segments. Scenario buckets include conservative, consensus, and aggressive technology substitution cases.
-
Primary data: Plant‑level capacity tracking, interviews with producers and OEM procurement leads, and proprietary pricing feeds for key precursors and salts.
-
Validation: Cross‑checking against public disclosures, regulatory filings, and transaction activity to ensure triangulation of capacity and commercial commitments.
Market structure and competitive dynamics — an executive snapshot
The market displays moderate top‑end concentration: the three largest players command a majority position, and the five largest account for a substantive, but not overwhelming, share of global supply. This structure produces a market that is neither a fragmented commodity race nor a closed oligopoly — instead it favors technically capable firms that can combine scale with purity, localized manufacturing, and strong customer qualifications.
-
Mitsubishi Chemical Corporation (Tokyo) — a legacy player with high‑purity liquid electrolytes and recent capacity initiatives aimed at serving North American cell makers that require localized supply. Their technology and global footprint make them a reference competitor on quality and compliance.
-
Green Energy Origin (GEO) (Weinheim) — rapidly expanding through asset acquisitions and integration of upstream inputs. Their strategy blends European and North American manufacturing to capture tier‑1 EV and stationary storage contracts.
-
Guangzhou Tinci Materials (Guangzhou) — a vertically integrated Chinese incumbent offering a broad portfolio of salts, additives, and electrolytes, with accelerated push into North America to secure OEM agreements.
-
Shenzhen Capchem, Shanshan (Dongguan), Soulbrain (Seoul), Guotai‑Huarong (Zhangjiagang), Panax Etec, Shandong Shida Shenghua, UBE, and BASF — each brings differentiated capabilities in purification, additive know‑how, or scale. The competitive field favors firms that can marry formulation IP with qualifying supply chains for automotive grade cells.
Recent strategic moves underscore the market dynamics executives must internalize: a notable asset transfer completed by Green Energy Origin in mid‑2026 that accelerates their North American footprint, and major greenfield and long‑term supply commitments by vertically integrated Chinese producers to service global OEM programs. These transactions are emblematic of two converging forces — capacity consolidation and geographic rebalancing — that will shape supplier selection and bargaining power in 2026.
Raw‑material volatility and regulatory signals — immediate tactical considerations
-
Price and supply risk: Key precursor pricing experienced sharp movements in the 2025–H1 2026 window. Such volatility compresses predictability for margins and favors producers with recycling, in‑house synthesis, or secured long‑term purchase agreements. The report models multiple raw‑material price paths and their effect on pass‑through mechanics to battery makers.
-
Policy and localization: Announcements of new North American manufacturing facilities and incentive‑driven localization have direct implications for cell‑maker sourcing strategies. Some projects have proceeded; others have been deferred or cancelled, signaling a reallocation of risk and capital that buyers and suppliers must track continuously.
Strategic playbook: recommended actions for 2026
-
Producers: Prioritize investments that shorten OEM qualification timelines (local labs, sample lanes), secure upstream inputs via long‑term contracts or JV structures, and selectively pursue bolt‑on acquisitions to scale purification capability.
-
OEMs and Tier‑1 battery integrators: Implement multi‑tier sourcing strategies that balance a small number of qualified strategic suppliers with a broader pool of qualified backups to mitigate single‑point supply disruptions.
-
Investors and PE: Use our risk‑adjusted valuation templates to screen targets for IP defensibility, contract stickiness, and the ability to meet automotive‑grade traceability and safety certifications.
-
Policymakers and regional planners: Recognize that electrolyte supply is a critical enabler of battery sovereignty. Incentivizing not just cell assembly but the upstream electrolyte and salt ecosystem materially improves local resilience.
How to use the full report in your 2026 planning cycle
-
Integrate our scenario outputs into board‑level capital allocation decisions and rolling 18‑month operating plans.
-
Use the supplier scorecards as a short‑list for qualification and commercial negotiations; adopt the procurement templates and hedging playbooks for immediate cost containment.
-
Leverage the M&A shortlists and diligence checklists to accelerate deal screening and reduce time to close for strategic acquisitions.
Next steps & how we can help
The full PW Consulting report contains the granular segment breakouts, downloadable financial models, plant‑level capacity schedules, and proprietary scenario files that corporate and investment clients use to make binding 2026 decisions. This introduction is designed to outline the decision‑relevant insights and to demonstrate the rigor of our approach while reserving the detailed datasets for the report and client workshops.
To move from insight to action in 2026, we recommend: commissioning a bespoke supply‑chain stress test, scheduling a supplier qualification acceleration program, and running a focused M&A sprint using our target shortlists. Contact PW Consulting to access the full report, the Excel model, and to arrange a workshop that aligns the findings to your firm’s strategic priorities.
For detailed analysis of this topic, please visit the official page: Lithium Ion Battery Electrolyte Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com